
Disclaimer: The views and opinions expressed in this blog are solely my own and do not reflect the views, policies, or positions of any organization with which I am affiliated. This blog is purely for informational purposes and should not be used as definitive advice. All facts, figures, and data mentioned within this blog post are derived from various sources accessible to the public and are not independently verified by me. While every effort has been made to ensure the accuracy of this information, it should be used as a guide only and should be cross-verified with other reliable sources. Please use this information responsibly and with discernment.
Executive Summary
The Software-as-a-Service (SaaS) industry in India is witnessing substantial growth, with an ARR of $12B-13B and a CAGR of 18-24%. This sector, accounting for 16% of total funding in India at the end of 2022, is expected to reach $50-$70 billion dollars in ARR by 2030, supported by increasing internet speeds, cloud software adoption, and maturing tech talent.
Despite economic challenges, SaaS investments in India have seen an 11% YoY rise, reaching $5 billion in 2022. This was fostered by the resilience of SaaS companies and their attractive burn multiples, encouraging investors to increase their share in SaaS investments.
The SaaS industry can be broadly segmented into horizontal business, horizontal infra, and vertical business, each offering unique value propositions and market share. The 'build local, sell global' strategy has become prevalent, where products achieve PMF in India and then focus on expanding to international mature markets.
Moreover, with the advent of COVID-19, a shift from Sales & Marketing driven growth to Product-Led Growth has been observed, leading to a reduction in S&M expenditure. This, along with stringent fund availability, has led to the optimization of burn rates and careful planning of scaling strategies.
The Indian SaaS industry also faces its own set of challenges, including the risk of a US default, scarcity of talent expertise in early-stage SaaS and domain-specific fields, and data security concerns.
Despite these challenges, the industry is poised for immense growth and the potential for Indian SaaS companies to gain a significant position in the global landscape by 2030 is high. The companies spotted in this thesis are expected to emerge as the leaders of this new era.
Introduction
The Software-as-a-Service (SaaS) industry can be defined as a paradigm where software is distributed over the internet rather than being packaged to its customer. This approach has proven more effective in the previous decade courtesy of rising internet speeds, increasing cloud software adoption, and maturing tech talent in India.
The Indian SaaS industry is growing at a CAGR of 18-24% globally as well as a domestic market CAGR of 30-35%, with its US and UK counterparts growing at almost half the rate. The SaaS industry funding represents 16% of the total funding in India at the end of 2022 up from 11% in the past year. 70% of the investors are focused on increasing their share in SaaS investments in the coming years given its resilience in strong headwinds and the potential of reaching $50-$70 billion dollars in ARR by 2030. The global SaaS industry is expected to reach $382 billion dollars in ARR by 2030.
Market Analysis
The SaaS industry in India stands strong as of 2022 with an ARR of $12B-13B and a CAGR of 18-24%. Out of this, 70-80% of the revenue is generated overseas. This has prompted the founders to tweak their GTMs with an India-for-the-world model where India becomes a test-bed for the companies to achieve PMF and GTM is focused on expanding outside the country.
Out of the 1600 startups funded in the last 5 years, only the Top 18 companies have reached $100M+ ARR, defined as 'Centaurs' by Bessemer Venture Partners in their report. This is the range where most US companies decide on an IPO. Most Indian Centaurs are currently facing challenging conditions for IPOs due to the prevailing economic recession.
The investors injected funds of about $5 billion in 2022 which was an 11% Y.o.Y. rise over the past year despite global funding winter and the massive 22% drop in total tech investments in India. The burn multiple (~Net new ARR / Net Burn) of 80% of these companies is said to be less than 1.5x, which combined with the high growth rates makes the industry an attractive vehicle for investors to hop on.
Sectors
The SaaS industry is broadly divided into three broad segments based on the breadth and depth of the problems addressed.
Horizontal business (70% of total market share)
Tools that help solve problems and have applications across diverse industries
Examples:
| Segment | Late Stage | Early Stage |
|---|---|---|
| CRM & Sales | Freshdesk, LeadSquared | [24]7.ai, Nexweave |
| ERP & Finance | IBSFintech, ChargeBee | Spotdraft, Zaggle |
| HCM | Keka, Darwinbox | Plum, Xoxoday |
| SCM | Locus, FourKites | SupplyNote, Intugine |
| Content mgmt | HubSpot, Invideo | Scenes, Bellplus Media |
| Communication | Asana, TroopMessenger | Cubyts, Talkie, Flock |
| E-commerce enablers | ElasticRun, Unbxd | GoKwik, Bizom |
| Workflow mgmt | Newgen | Maya Labs, Hubblr |
| Collaboration tools | Kissflow | EisenVault, Dyte |
Horizontal infra (15% of total market share)
Tools that help in scaling the tech industry by assisting in application development, testing, API management, analytics/BI, and cybersecurity.
Examples:
| Segment | Late Stage | Early Stage |
|---|---|---|
| Application Development | Appnomic, Esper | ShepHertz, Myraah |
| API Management | Postman, Hasura | Firecamp, apibeats |
| Testing tools | BrowserStack, LambdaTest | HyperTest, LM Tools |
| Cybersecurity | Securonix, Seclore | Sequretek, Priva Sapien |
| Data, Analytics, and Business Intelligence | Druva, Paperflite, Manthan, CloudCherry | Locobuzz, Toplyne |
Vertical business (15% of total market share)
Tools that help solve problems in a single industry like healthcare, hospitality, logistics, etc.
Examples:
| Segment | Late Stage | Early Stage |
|---|---|---|
| Healthcare & Wellness | API Holdings, Innovaccer | Arintra, Kenko |
| Media & Entertainment | Playtonia, Hippo Video | 100ms, Prime Focus Tech |
| Education | Byju's, Unacademy | Next Education, Toddle |
| Real Estate Tech | Facilio, PropTiger | Proptor, Enlite research |
| Hospitality Tech | Hotelogix, IBS Software services | eGlobe solns, Horeca Stop |
Trends
Infra over businesses
The horizontal business segment has the largest market share within the SaaS industry but the specialization of India in tech (~1.5x the number of developers compared to the US) boosts the horizontal infra segment's potential massively. Startups focusing on DevTools (Application development, API management, Testing), Cybersecurity, and Data Analytics/BI will be the norm to build for the domestic market.
For the world!
The companies have a 'build local, sell global' strategy where the product is developed and PMF is achieved in India, but as the company scales, the GTM is focused on international mature markets. India is en route to rapid growth in the number of early-stage companies for different niches while the growth-stage companies prep for favourable economic conditions to expand outside the border.
Grow, grow, grow.... stop!
High-growth SaaS startups (>50%) have 50%+ Sales & Marketing (S&M) spend / Revenue share fetching them higher valuation (EV/Revenue) multiples. This is enabled by upsells/cross-sells, alliances and partnerships, and expansion to international mature markets (US/UK). Since global headwinds have caused a slowdown in the expansion dropping sales efficiency, the founders are focused on existing product innovation, new product development, and better pricing policies. Once the headwinds turn directions, we should see considerable growth in S&M spending through better GTMs.
Product Led Growth
Prior to the Covid-19 pandemic, product expansion was predominantly driven by Sales & Marketing teams. However, in the wake of Covid-19, organizations have pivoted towards less resource-intensive methodologies such as Product-Led Growth. This strategic shift can significantly reduce Sales & Marketing expenditure, becoming an efficient component of the revenue generation arsenal, leading to a portfolio of Product-led Sales and PLG.
Burn baby burn!
Burn multiple is defined as the Net yearly burn / Net ARR gain. Ultragrowth businesses in the country are managing to keep it low under ~1x. With the stringent fund availability, startups will be mindful of the burn rate, causing the burn rate to drop as they plan their experiments wisely and optimize the scaling ideologies.
Talent overdrive
The recent layoffs have saturated the market with a high density of talent. Although the density is high, there is a gap in product management and developer candidates given the lower average years of experience as compared to international peers. This gap will close given the advent of upskilling programmes making India ready for the 3-6x requirements in the workforce by 2030.
Investment Strategy
Criteria
Each SaaS company has a few technical and non-technical criteria which would make them suitable for investments in the pre-seed stage:
- TAM - High potential startups need a good TAM to be investible - ~1B+
- Sector - Horizontal infra and vertical businesses are untapped and have a huge untapped potential as compared to horizontal businesses
- Team - The team plays a crucial role in an early-stage setup
- Technology - The product development practices and tech allows the companies to experiment, pivot, and iterate quickly in the early stage, and scale and create new offerings in the later stages. (Bonus if they have generative AI and LLMs, jk :P)
- GTM Maturity - An inefficient GTM plan would tumble all the metrics following this one
- Growth - Although SaaS has steady pacers, high growth companies are synonymous with low burn, high valuation - ~50%+
- Net Revenue Retention - High-potential startups should consider churn along with growth to get an overall business picture - ~120%+
- Capital Efficiency - Burn optimization is a key focus in this downturn and efficiency would be equivalent to the extra dollars earned per unit dollars burned - ~100%+
- Gross margin - A high gross margin clears the path to profitability and efficiency which has been seen for larger startups - ~65%+
- CAC Payback - The average time per customer it would take the company to recuperate the CAC spent is low for highly efficient startups and determines the pace - ~<12 months
Exit Strategy
- IPO - Startups above $100M ARR with good health can be suggested to be publicly listed. Eg: Freshdesk
- M&A - Startups in crowded markets with established players can either disrupt or be acquired by the sharks in those markets. Eg: Billdesk
- Secondary Sale - Startups that have metrics below the fund standard or have fallen out from the thesis.
Investment Opportunity Analysis
Some startups to invest in (with memos)
Amigo
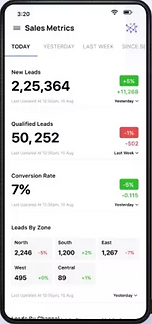
TAM - ~$13B
Sector - Vertical business focused on D2C (Has horizontal offerings). Experimenting with a hiring portal.
Team - Ex-Zomato, Matrix, IIT Kgp, IIM A
Technology - Integration with 20+ platforms. Provides features of exporting, dashboarding, data storage, no-code usage, tracking, and alerts. Seamlessly integrated with GSheets. Insight offerings can be improved. The hiring portal uses ML to assess candidates and provides a good UX through pre-assessment and simplified results to recruiters and managers who have millions of applicants.
GTM - PLG model for self-serve growth with multiple pricing tiers and limitations with separate offerings for enterprise. Maturity can be reached through better sales motion and outbound sales. The hiring portal can be a really good offering if priced correctly and marketed with a dedicated S&M team.
Notes - Real-time reporting with insights can reach a high scale as a powerful business intelligence tool. Helps in determining business health and day-to-day actions. Needs vertical-specific dashboarding to create familiar experiences for each industry/use case through better templates. The hiring portal has potential with a good product with high chances of PMF.
Honourable mentions:
- Baselit
- Finayo
- Crest
- Blup
- AuraML
- Datazip
Risk Assessment
- US Default Risk - The US economy stands in a dire state right now and may default causing the mature markets to reflect accordingly and crash. This may lead to further delays in GTM strategies, a slowdown in growth, and a few companies shut shop.
- Talent scarcity - Scarcity of talent expertise in early-stage SaaS and domain-specific fields may lead to a draught slowing down the product development processes and eventually prolong the PMF phase.
- Data security - Security and privacy of data are becoming more and more important as vulnerabilities scale with the applications deployed online.
Conclusion
The SaaS industry is going nowhere with the level of growth and quality of businesses created. While there is a slowdown, India is ready for selling the world and growing to a top spot in the SaaS landscape by 2030. The companies spotted in this thesis are my bets to grow into the behemoths of the next era.
Feel free to reach out to me on LinkedIn or email me at mohanish3@gmail.com for a discussion!
You can read more about me and my blogs here.
Sources